The month of September has been surprisingly quiet and relatively flat. That’s a relief given this month’s history of ugly selloffs. There appear to be early signs that Growth is starting to outperform Value, a ratio we watch closely for market context. It isn’t confirmed yet, but it wouldn’t take much for that relationship to put us back into growth mode.
One of the bigger headwinds holding back the market right now appears to be the price of crude oil futures moving back above $100. The spike peaked on September 15th, and looks to be calming back down below the $90 price level. We’ve seen the stock market struggle when that number gets too high, so seeing it back off has been a positive sign for the second half of the month.
The Federal Reserve raised the Fed Funds rate by 0.25% as expected, and signaled another rate increase of 0.25% would likely occur in the near term. This matches theTwo-Year Treasury Yield I’ve mentioned many times (thanks to Tom McClellan) and with the chart shown at the end of my September market commentary video.
Our guess is that we are not out of the woods just yet. We still have to get through the often spooky month of October and the midterm elections before the historically strong “best eight months” of the four-year presidential cycle typically begin.
This month’s chart compares the fed funds rate (the smoother line) with the 2-year U.S. Treasury yield (the choppier line). Even as the Fed has raised rates in line with the 2-year yield, that yield has kept moving further away. That suggests more than one additional hike may be needed unless the 2-year reverses course.
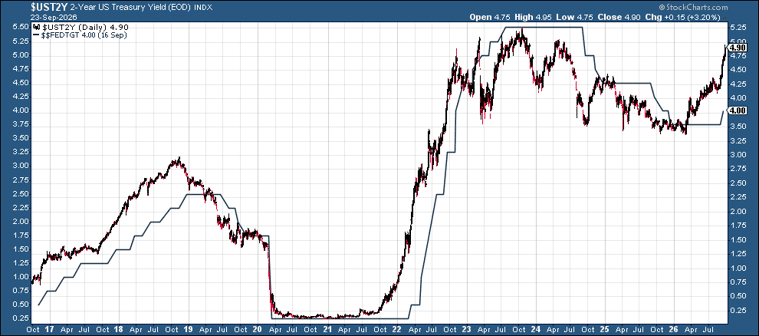
Ten-Year chart of the 2-Year US Treasury Yield compared to the Fed Funds Target Rate (Source: FastTrack.net)
Our Shadowridge Long-Term Trend indicator turned negative August 31st, having been positive since early April.
Our Mid-Term Cycle indicator leans negative, recently dipping below the range it has been in for a few months.
As of Wednesday night (September 23rd, 2026), our Shadowridge Dashboard showed Positive to Negative market sectors as 3 to 8. Technology, Communications, and Healthcare make up the positive sectors.
Only one of the Ten RGB Bond Indices are trending positive, above their 50-day Moving Average. The only positive bond sector is Floating Rate. I talk about that one often in our monthly webinar.
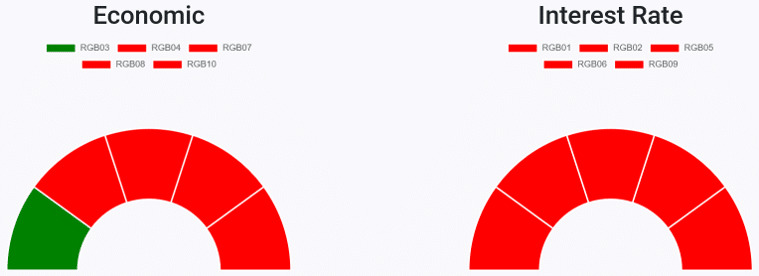
RGB Economic and Interest Rate Sensitive Bond sectors (Source: ShadowridgeData.com)
With the Federal Reserve raising rates again, the bond market looks even less interesting to us than it did earlier this year. Floating-rate is still the only bond sector in a positive trend, so in our view, there is little reason to stay diversified across the rest of the space. We believe that money market funds may be a better place to park cash or to stand in for a fixed-income allocation given current conditions.
Bottom line: The market is holding up relatively well given the underlying sector weakness and the NYSE advance-decline data we watch. This is still a tough stretch of the year, so more volatility would not be a surprise even though we have seen relatively little of it so far. We stay cautious until after the midterm elections. Historically, the odds of a stronger market begin to rise soon after that.
Stay safe out there!
Important Disclosure Information
Please remember that past performance is no guarantee of future results. Different types of investments involve varying degrees of risk, and there can be no assurance that the future performance of any specific investment, investment strategy, or product (including the investments and/or investment strategies recommended or undertaken by Shadowridge Asset Management, LLC [“Shadowridge]), or any non-investment related content, made reference to directly or indirectly in this commentary will be profitable, equal any corresponding indicated historical performance level(s), be suitable for your portfolio or individual situation, or prove successful. Due to various factors, including changing market conditions and/or applicable laws, the content may no longer be reflective of current opinions or positions. Moreover, no portion of the foregoing content serves as the receipt of, or a substitute for, personalized investment advice from Shadowridge. Shadowridge Asset Management, LLC is an investment adviser registered with the Securities and Exchange Commission. Neither Shadowridge’s investment adviser registration status, nor any amount of prior experience or success, should be construed that a certain level of results or satisfaction will be achieved if Shadowridge is engaged, or continues to be engaged, to provide investment advisory services. Shadowridge is neither a law firm, nor a certified public accounting firm, and no portion of the commentary content should be construed as legal or accounting advice. A copy of the Shadowridge’s current written disclosure Brochure and Form CRS discussing our advisory services and fees continues to remain available upon request or at www.shadowridgeinvest.com. Please Remember: If you are a Shadowridge client, please contact Shadowridge, in writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you would like to impose, add, or to modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. Please Also Remember to advise us if you have not been receiving account statements (at least quarterly) from the account custodian.
Historical performance results for investment indices, benchmarks, and/or categories have been provided for general informational/comparison purposes only, and generally do not reflect the deduction of transaction and/or custodial charges, the deduction of an investment management fee, nor the impact of taxes, the incurrence of which would have the effect of decreasing historical performance results. It should not be assumed that your Shadowridge account holdings correspond directly to any comparative indices or categories. Please Also Note: (1) comparative benchmarks/indices may be more or less volatile than your Shadowridge accounts; and, (2) a description of each comparative benchmark/index is available upon request or at www.shadowridgeinvest.com.